AI Agents Can Now Act for You. Who Is Going to Keep Them in Check?
For most of the Internet era, giving a website access to your digital life was a relatively benign thing to do. You might allow a budgeting app to track your spending, give a travel app access to your calendar, or let an email service scan your inbox to filter out spam. The software could see things, organize important information, and make recommendations. But for the most part, a human was still required to press a button to get a result.
But with the recent release of Muse from Meta Platforms and its astounding acceptance among consumers, artificial intelligence is beginning to change this relationship entirely. Until now, most consumer AI apps were used to answer questions and perform deep research. But Meta’s new personal agent is designed to do a lot more with minimal human intervention and oversight, which begs the question: who is going to keep the agents in check?
Read More
AI Has Already Disrupted the Stock Market. Now It's Coming for the Bond Market.
For decades, bonds have played a fairly straightforward role in any investment portfolio. While stocks are expected to provide growth—in exchange for some occasional volatility—bonds are expected to provide stability and predictability, allowing a diversified investor to sleep peacefully.
But this year, the bond market has been anything but boring. Both short- and long-term treasury yields have moved up in tandem as inflation expectations, Federal Reserve policy, and the federal government's substantial borrowing needs have all come into sharper focus simultaneously. Then, add to the mix that some of the largest technology companies in the world have begun borrowing money at a pace rarely seen outside of a major financial crisis, driven by the staggering capital requirements of the AI buildout.
Read More
Life Insurance Creates an Inheritance, Not Generational Wealth
For high-earning couples who have spent decades accumulating assets, one of the most common measures of financial success is whether they will eventually leave something meaningful behind for their children. And for many, life insurance is expected to play an important role in accomplishing that goal.
A large life insurance payout can create a multi-million dollar inheritance overnight, making it entirely possible for parents to leave their children in a much better financial position than they were in at the same age. But leaving behind a large inheritance and creating generational wealth are not necessarily the same thing.
Read More
Cybersecurity’s Consolidation Era Has Arrived and AI Is Accelerating It
Artificial intelligence (AI) is poised to create one of the largest identity-management challenges enterprises have ever faced. For decades, cybersecurity programs were designed primarily around human users, with employees receiving credentials that determined what systems, applications, and data they could access.
But as companies deploy an increasingly large number of AI agents, they must manage a rapidly expanding universe of non-human identities, creating new security challenges. That shift could make identity security one of the most important areas of cybersecurity, and thus one of the most lucrative investment opportunities this decade.
Read More
When You Earn $1 Million or More, the Rules of Personal Finance Change
From a financial planning perspective, there is nothing magical that happens once an individual or couple breaches the $1,000,000 mark with respect to their gross income. There is no special million-dollar tax bracket, nor does the IRS suddenly hand you a different rulebook once the first seven-figure W-2 arrives.
In fact, by the time someone earns $1 million in one calendar year, they have already crossed most of the income thresholds that materially affect their taxes. However, for senior leaders who reach this level of compensation, the basic rules of personal finance start to change entirely.
Read More
Why Has It Gotten So Hard to Be a Long-Term Investor?
Investing used to be simple. All you needed to do was buy good companies, add to them over time, ignore the noise, and allow the laws of compounding to do the rest. Now, although none of those principles has stopped working, following them has gotten a lot harder.
Prediction markets, sports betting, and crypto have all exploded in popularity over just a few short years, and the ability to access such speculative bets has been lumped in with traditional financial instruments like stocks. When this sort of risk-taking behavior is normalized and seen as a sustainable long-term strategy, it inevitably begins to spill over into traditional financial markets.
Read More
Why Investors Can’t Stop Buying Stocks After Everyone Else Already Has
The savviest investors know that they are not supposed to buy a stock simply because it has gone up a lot and that last year’s winner will not necessarily be this year’s. By the time a particular investment has become the subject of podcast conversations and social-media posts, all the easy money has likely already been made.
That said, every market cycle produces the same behavior. A stock begins rising enough to attract some attention. Analysts trip over themselves to be the first to increase their price targets. Media coverage of the company and its CEO expands. Finfluencers, who happened to have bought the stock early begin posting extraordinary gains online. And eventually, people who had no interest in the company just six months earlier suddenly become convinced that they are missing out on the next big thing.
Read More
Retail Investor Portfolios Are Beginning to Look More Like Parlays than Strategies
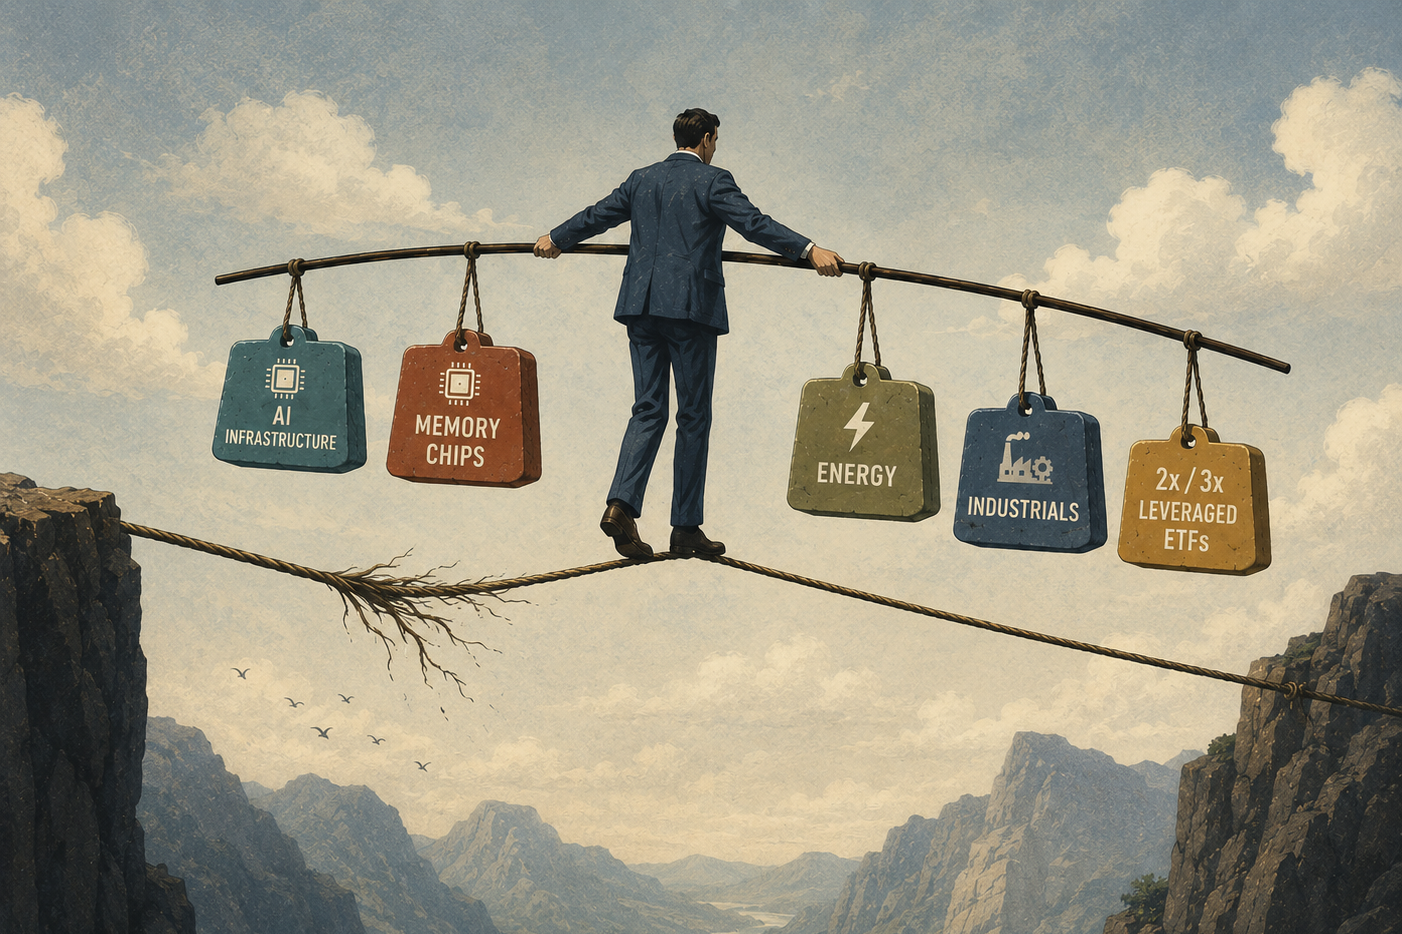
Spend enough time in online investing circles, and you will encounter portfolios that read less like well-researched investment themes and more like multi-game parlays. Individual investors are layering 2x levered single-stock ETFs tied to Korean memory chip manufacturers on top of 3x levered semiconductor index funds that are all housed within the same brokerage account, often purchased on margin.
And to be fair, for a time, it works. Momentum has a way of validating behavior that would otherwise seem reckless. But what seasoned investors know is that these types of flashy trades have a way of working, right up until the moment they don’t. The same leverage and concentration that amplify gains on the way up tend to accelerate losses just as quickly when sentiment shifts. And by the time that shift becomes obvious, it’s usually too late for the investors who jumped in last.
Read More
What to Do When You Realize You’ve Saved Too Much for Retirement
An increasing number of retirees are confronting an unexpected reality. What was not obvious during their working years—even if they were high earners throughout much of their career—often becomes clear in their 70s or 80s: that they may have saved far more for retirement than they are likely to spend over the remainder of their lives.
For decades, the dominant narrative in personal finance has been one of scarcity. Investors have been inundated with messaging designed to evoke anxiety and uncertainty, prompting questions such as, “Will I have enough?”, “Will my portfolio last?”, and “Should I be saving more?” Today, however, a growing number of retirees are confronting a very different question: “How much is too much?”
Read More
How to Protect a Concentrated Stock Position Without Selling It
There’s a moment that tends to catch even the most financially sophisticated executives off guard. It doesn’t usually happen when the first equity grant vests, nor when the stock doubles or triples. It happens years later when you finally realize that what once felt like a modest equity award has quietly grown into a multi-million-dollar position.
At that point, the question is no longer how much higher the stock might climb, but how much of your financial future should remain exposed to the fortunes of a single company. That question becomes especially important when the market is in a frenzy, valuations are elevated, and market leadership is narrow, as is the case today. While selling shares outright may be restricted, tax-inefficient, or emotionally difficult, options can provide another path.
Read More
Here's the First Thing You Should Do Following an IPO
The days following a major Initial Public Offering (IPO) are often characterized as first-day pops, valuation milestones, and trading volume. But for the employees and early stakeholders, the experience is far more personal.
When SpaceX officially went public, it did not just mark the largest and most anticipated IPO of all time. It also helped make an estimated 4,000 current and former employees bona fide millionaires. But what tends to get far less attention is the set of difficult decisions that follow.
Read More
Many High Earners Use the Short-Term Rental Loophole Wrong
For high-income earners who routinely receive large bonuses, have significant RSU vesting events, or experience a once in a lifetime liquidity event such as an IPO, few tax strategies generate more attention and confusion online than the so-called "short-term rental loophole.” This loophole allows bona fide real estate investors to use losses generated by a short-term rental property to offset ordinary income.
The strategy can sound almost too good to be true. In some cases, it is; but in other cases, the short-term rental loophole can be a powerful planning opportunity. The key is understanding what it actually does, who it is designed for, and why the greatest benefit may not be reducing taxes presently but rather creating an opportunity to reposition wealth more tax-efficiently for decades to come.
Read More
Tech Layoffs May Have More to Do with the Cost of RSUs Than AI
The world’s largest technology companies—Alphabet, Microsoft, Amazon, along with Meta Platforms—are widely perceived to be spending at unprecedented levels to secure their positions in what many believe will be the defining technological shift of the next decade. Nevertheless, there is a narrative forming around the artificial intelligence (AI) arms race that seems incomplete.
The assumption—reinforced almost daily by headlines and prepared statements on quarterly earnings calls—is that nearly all this capital is being funneled into the infrastructure needed to power increasingly complex AI workloads. But buried within the financial statements is the sobering reality that a meaningful portion of the capital currently being raised isn’t going toward AI infrastructure at all. Instead, it’s going to the IRS.
Read More
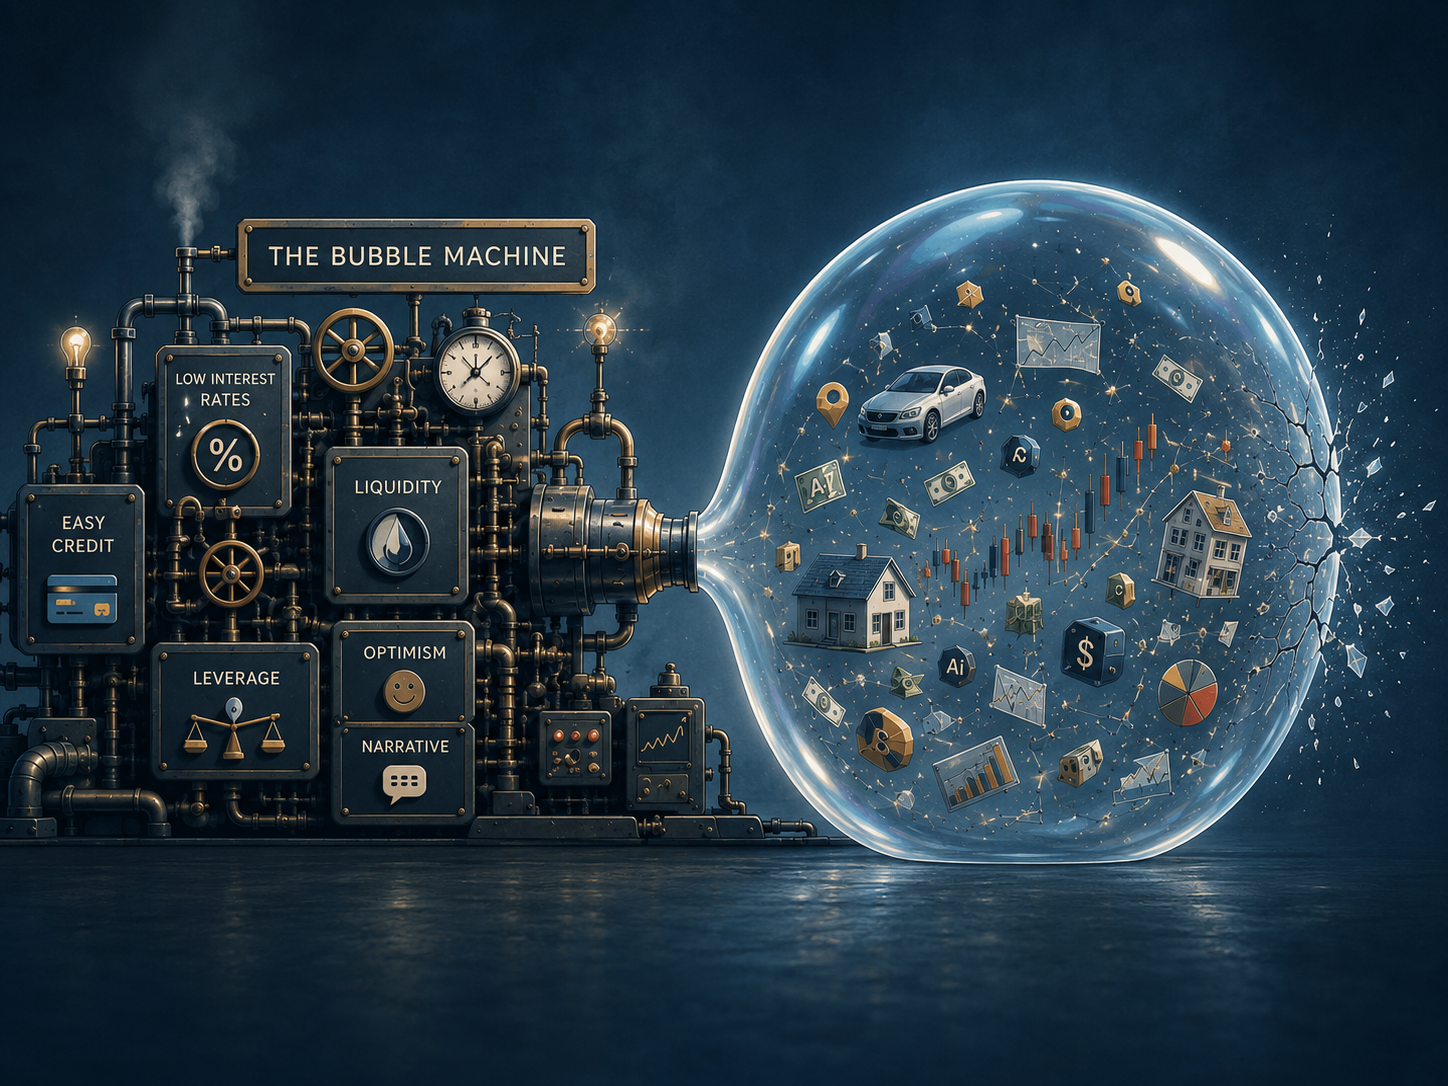
The Anatomy of a Stock Market Bubble
A stock market bubble is best defined as an episode of rapid price appreciation, followed by an equally dramatic decline. While these moments are often framed as anomalies, they are actually recurring features of the system. And while each cycle is assigned its own narrative, the underlying mechanics tend to look strikingly similar.
Boom. Bust. Repeat. This is the rhythm of financial markets, tending to become most visible only in hindsight. Understanding that rhythm won’t allow you to predict the exact peak or trough. But it does offer context for recognizing where you might be in the cycle, which is arguably more valuable.
Read More
The MalcolmOnMoney Guide to Microsoft’s Early Retirement Offer
Early retirement offers usually include some combination of severance, healthcare continuation, retirement plan decisions, and special treatment for certain forms of compensation. The exact terms vary by company, but most offers are built around a simple tradeoff, whereby the company offers some financial support to leave voluntarily. In exchange, you agree to end your employment on a defined timeline.
In a typical early retirement package, the severance component might be based on years of service, weeks of pay, or job level. Some companies also offer extended healthcare coverage, accelerated 401(k) vesting, pension enhancements, outplacement support, or more favorable treatment of unvested stock.
Microsoft’s offer appears more generous than many standard early retirement packages in a few important ways. But the detail likely to matter most for many long-tenured Microsoft employees is the treatment of company stock.
Read More
The Number of Millionaires Has Reached an All-Time High in the U.S. Do You Stand to Leave More of It to Your Kids or the Government?
By most recent estimates, the U.S. is home to more than 22 million millionaires, which reflects the highest figure ever recorded. This growth has primarily been fueled by a decade-long rise in both equity markets and home values. Yet beneath that headline sits the sobering reality that a meaningful share of that wealth may never reach the next generation, the way it’s intended.
For many high earners who have saved diligently over the course of their career, the difference between a well-structured estate plan and a neglected one can translate into hundreds of thousands—or even millions—of dollars unintentionally being gifted to the government. That means the biggest threat to the largest expected wealth transfer in history isn’t that markets reverse or that spending runs rampant, but an absence of planning.
Read More
Don’t Sleep on Dividends. They’re Not Just for Boomers.
For younger investors coming into a stock market that is defined by the outsized gains of high-growth technology companies resulting from the IPOs of venture-backed decacorns, dividend-paying stocks are often viewed as a thing of the past. These stocks are mistakenly considered appropriate only for retirees seeking income—not for those still in the accumulation phase of their careers.
While understandable, this perception is incomplete. It reflects a short-term view of investing that completely misses what dividends signal about the underlying businesses that pay them. But when viewed through a more comprehensive lens, dividends are not only a source of income; they are also a byproduct of fiscal discipline and long-term financial strength.
Read More
Microsoft is Offering Some Employees Early Retirement. Should You Take It?
For the first time in its 51-year history, Microsoft just announced that it will be offering voluntary retirement to thousands of its employees in the U.S. An estimated 7% of its U.S. workforce will be eligible for the buyouts, which includes personnel whose years of service plus their age totals 70 or more.
While the move by Microsoft may feel uncharacteristic for a firm that has a history of celebrating its long-tenured workforce, it also reflects a practical response to the current market dynamics. Big tech companies like Microsoft have been looking for ways to trim their expenses as they pour hundreds of billions of dollars into building out their AI infrastructure for the future and reallocate resources toward the next phase of growth.
Read More
Running Out of Time to File Your Taxes? Here’s Why an Extension May Be the Smarter Move
There is a particular kind of pressure that sets in during the final days before the tax filing deadline, and it’s equal parts urgency and avoidance. For many taxpayers, the realization that they’re up against a hard deadline, paired with the hope that it can still be wrapped up quickly is a source of anxiety.
For many taxpayers, especially those with increasingly complex financial lives, this is the moment when the temptation to “just get it done” using a do-it-yourself software solution sets in. But in reality, rushing through your tax filing might be the most expensive financial decision you can make.
Read More
Tech Workers: Activist Investors May Be Coming for Your Equity Compensation
In 2021—the early days of the current bull market—many software companies’ trading multiples seemed untethered from reality. At the time, however, very few shareholders complained that 15%, 20%, or even 25% of annual revenues were being paid out to company employees in stock-based compensation.
Equity grants were framed as a necessary cost of attracting top engineering talent, and buybacks designed to offset dilution were described as a sensible allocation of capital. But as the air has come out of many high-growth software names, and concerns mount that generative AI could commoditize swaths of traditional enterprise software, patience is wearing thin among the investor class.
Read More